This Dussehra, Conquer Your 5 Financial Ravanas
By Sagar Saroy
Ravana had ten heads. Rama kept cutting them off. They kept growing back.
The arrow that ended the war went to one place: the source.
Your money works the same way. This Dussehra, here are the five financial Ravanas most salaried Indians carry, why fighting them one at a time rarely works, and where to aim instead.
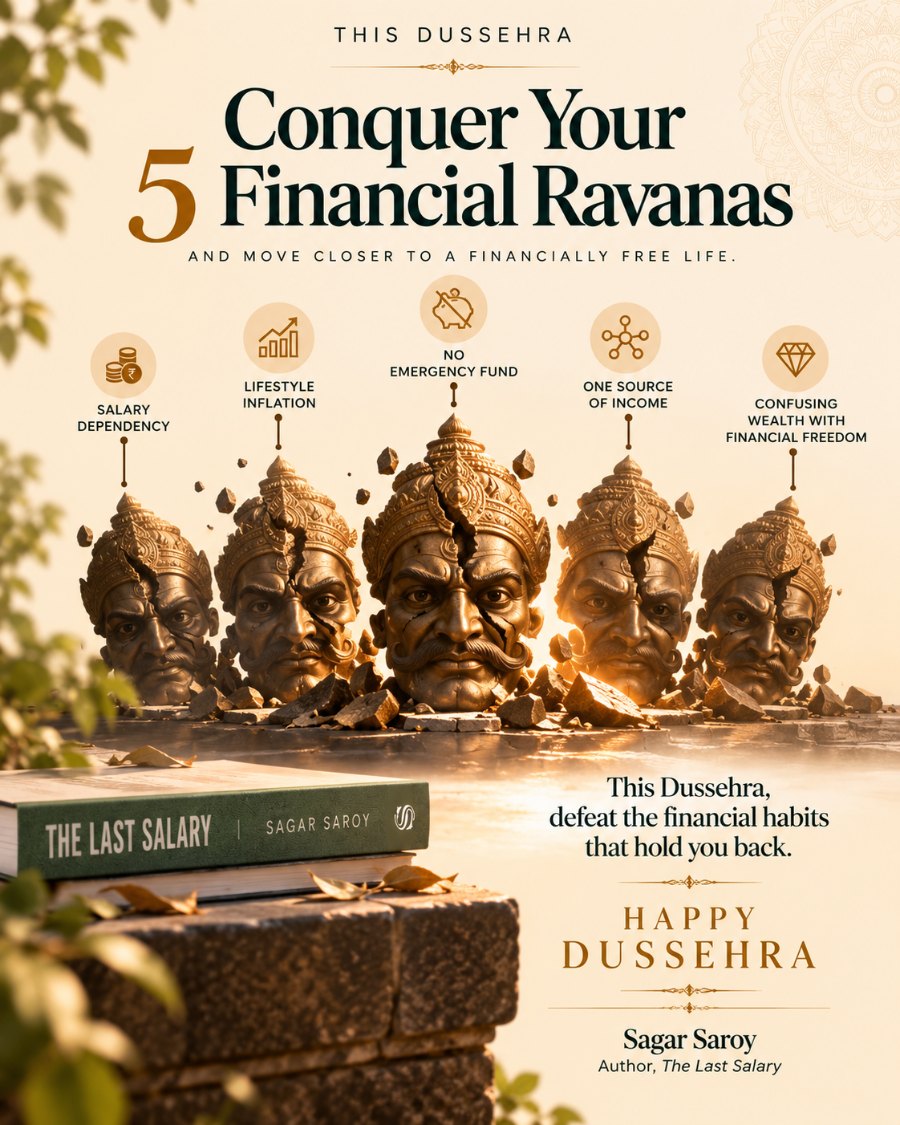
The 5 financial Ravanas
1. Salary dependency
One employer decides when your life stops being funded. A restructuring, a new manager or a health scare can switch off the only income your household has.
2. Lifestyle inflation
Every raise is spent before it arrives. A bigger flat, a better car, a costlier school. Each upgrade quietly raises the amount your Salary must cover, month after month.
3. No emergency fund
One hospital bill becomes a loan. Without several months of expenses set aside, every surprise turns into debt, and debt ties you even more tightly to your Salary.
4. One source of income
A single point of failure dressed up as stability. A steady Salary feels safe right up to the day it stops. Then it turns out to be the only thing that was holding the house up.
5. Confusing wealth with financial freedom
A ₹2 crore portfolio you must sell to pay bills is a number, not freedom. Wealth is what you own. Freedom is what pays you without being sold. When markets fall, a portfolio that funds your life forces you to sell at the worst time, as I explained in what I told ET Wealth about retiring into a market crash.
Why the heads keep growing back
Most people fight them one head at a time. A budgeting app for lifestyle inflation. An FD for emergencies. A bigger SIP for "wealth".
The heads grow back.
| Financial Ravana | The usual fix | Why it grows back |
|---|---|---|
| Salary dependency | Work harder for the next appraisal | The employer still decides |
| Lifestyle inflation | A budgeting app | Spending rises with every raise |
| No emergency fund | A fixed deposit | The FD is refilled from the same Salary |
| One source of income | A side hustle that needs your time | It stops the day you stop |
| Wealth mistaken for freedom | A bigger SIP | The corpus still has to be sold to pay the bills |
All five feed from the same source. Every rupee you spend still comes from one Salary.
Aim the arrow at the source
Build one income stream that pays you without your time and without selling the asset. It can start small:
- Rent from a property, or a share of one
- A small business you own, rather than one you have to run every day
- Your own skill, sold in your own name to a second buyer
You do not need to start rich. The first arrow is always smaller than the fear makes it look.
Track your progress with one number, your Freedom Score: monthly income from assets that arrives without selling, divided by monthly expenses. If your household spends ₹1,00,000 a month and your first income stream pays ₹10,000, your Freedom Score is 10%. Small, yes. But every point weakens all five heads at once.
My own Dussehra
Rental cash flow made me financially free at 45. I walked out of corporate life at 50. The full method is in my book, The Last Salary: Cash Flow, Not Corpus, and you can read the free chapter at TheLastSalary.com.
Happy Dussehra. May this be the year your money starts paying you.
Frequently asked questions
What are financial Ravanas?
Financial Ravanas are money habits that keep you dependent on a single Salary: salary dependency, lifestyle inflation, having no emergency fund, relying on one source of income, and confusing wealth with financial freedom.
Why does salary dependency matter even with a good job?
Because one decision you do not control can stop all of your household's income at once. A good job lowers the odds, but it does not remove the single point of failure.
What is the difference between wealth and financial freedom?
Wealth is the value of what you own. Financial freedom is when income from your assets covers your expenses without you having to sell those assets.
How can I start a second income stream without much money?
Start with what you already have: a skill you can sell in your own name, a share in a rental property, or a small business you own. The first stream can be small; what matters is that it does not depend on your employer.
How big should an emergency fund be for a salaried person?
A common guideline is at least six months of essential expenses, and more if your job is less stable or your family depends on one income. Keep it in safe, easily accessible places.
Disclaimer: This article is for education only and is not investment advice. Please speak to a qualified financial adviser before making any financial decision.